
Fitch Revises Nigeria’s Outlook to Positive, Anticipates Tinubu 2027 Election Win
Fitch Ratings has revised the outlook on Nigeria’s Long-Term Issuer Default Ratings (IDRs) to positive from stable and affirmed the IDRs at ‘B’.
According to the ratings note, the country’s Outlook revision reflects ongoing reform of the policy framework and Fitch’s increased confidence that momentum will not be disrupted by upcoming elections.
Fitch noted that Nigeria’s monetary and exchange rate reforms have supported greater naira flexibility, disinflation, and faster-than-expected FX reserve accumulation, while improved reserve quality enhances resilience to shocks.
Ratings analysts maintained that the continued implementation of reforms is strengthening monetary policy transmission and should support further disinflation, although inflation will remain well above peers.
Nigeria’s ratings reflect its large economy, a relatively developed and liquid domestic debt market, large oil and gas reserves and an improved macroeconomic policy framework.
The rating is constrained by weak governance indicators, high hydrocarbon dependence, high inflation, security challenges and structurally low government revenue relative to peers.
The revision of the Outlook reflects expected policy continuity, stronger external buffers, a restrictive monetary policy, and higher oil production, among other factors.
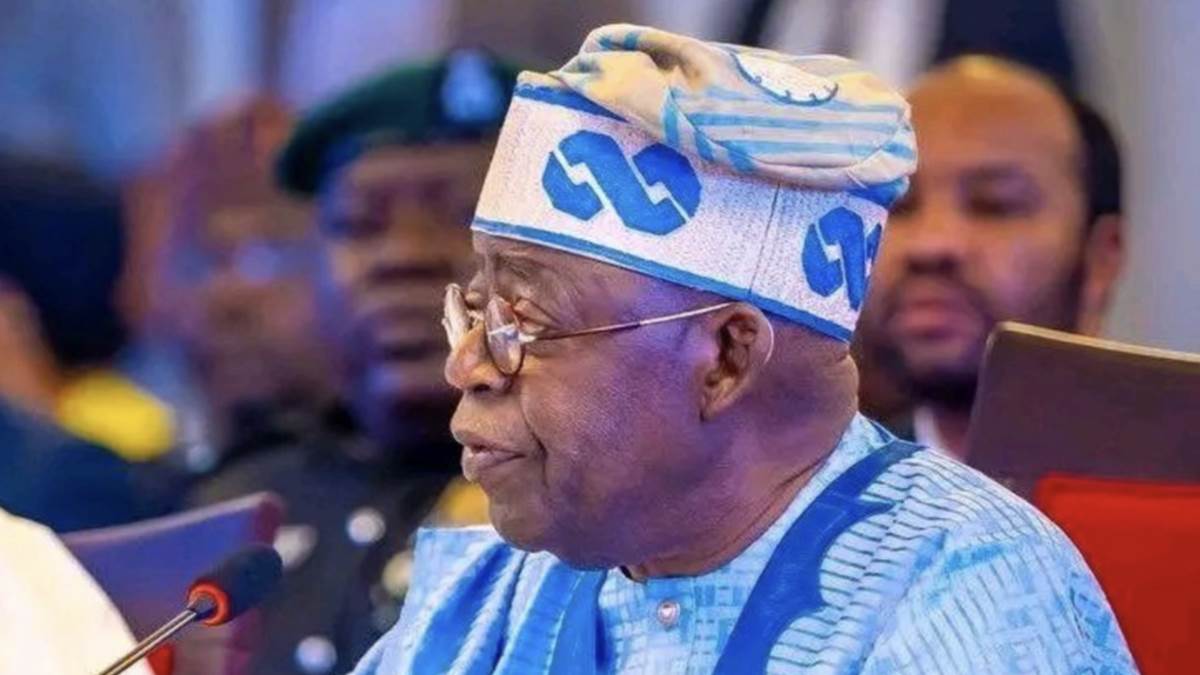
Fitch said the incumbents, President Bola Tinubu and others, are well positioned to win the early 2027 elections due to the ruling party’s control of the majority of Nigeria’s 36 states and a fragmented opposition.
“As a result, we expect broad economic policy continuity, including in relation to reforms that have contributed to improved policy credibility, higher external liquidity and enhanced resilience to external shocks.
“Risks to our baseline stem from significant policy slippage, including fiscal loosening, or weaker capital inflows or major social instability”, Fitch said.
Nigeria’s gross FX reserves rose to USD54.9 billion on 25 September 2026 from USD32 billion in mid-April 2024, supported by increased formalisation of FX transactions, strong portfolio inflows and higher export receipts and remittances.
“We forecast the current account surplus will widen to 6.4% of GDP in 2026, but we expect it to narrow in 2027 amid our expectation that global oil prices will fall to USD70/b from USD87/b in 2026.
“We expect reserve coverage to equal 6.3 months of current external payments at end-2026, and remain above peers in 2027-2028, although large net errors and omissions remain a source of uncertainty.
“Reserve quality has improved as the Central Bank of Nigeria (CBN) reduced its FX liabilities; it stated net FX reserves at USD34.8 billion at end-2025 from about USD4 billion at end-2023.
“We expect the naira to trade broadly around the current level through end-2026, despite the prospect of lower oil prices in 2027-2028”, Fitch said.
Rating analysts said they view the CBN’s September policy adjustment as a calibrated easing consistent with improving policy transmission.
Fitch noted that the retention of the 45% cash reserve requirement will continue to absorb local currency liquidity and limit credit growth, while the narrower policy corridor, broader access to open market operations and recent efforts to transition gradually towards inflation targeting should improve policy effectiveness.
“We expect the CBN to remain cautious amid high food and fuel prices and external risks, and we forecast average annual inflation to moderate, due to naira stability and tight monetary policy, to 15.4% in 2026, less than half the 2024 level, but well above the forecast ‘B’ median of 5.6%”.
The rating note stated that Nigeria’s crude production, excluding condensates, rose 10% qoq in 2Q26 and has met Nigeria’s 1.5mbpd OPEC target since May 2026, averaging 1.52mbpd.
“We expect production to remain around this level in the near term, supported by improved security and domestic investment, but below pre-pandemic levels.
“Dangote refinery’s ramp-up and rehabilitation of other facilities leading to increased production of refined products has reduced refined oil imports and FX demand, but limited domestic crude supply will partly maintain reliance on imported crude”.
Nigeria’s ‘B’ IDRs also reflect its wider 2026 fiscal deficit, high interest burden on moderate debt and non-oil growth, according to the rating note.
Fitch forecasts the general government (GG) deficit to widen by 0.5pp to 3.6% of GDP in 2026, driven by higher social, security, personnel, capex and state spending, despite likely capex under-execution.
Ratings analysts expect tax reforms to raise non-oil revenue to 7.5% of GDP (66% of government revenues) through improved administration, compliance and digitization, although implementation constraints will limit gains. GG revenue/GDP will remain below the projected ‘B’ median of 19%.
“We assume the deficit will be financed mainly through domestic sources, with over 70% of the borrowing target already raised. External financing will include official and commercial borrowing.
“The USD5 billion total return swap facility, of which USD1.5 billion has been drawn, raises potential contingent liability and liquidity risk, but these are presently mitigated by the limited disbursement and high international reserves”.
Fitch analysts expect the GG interest/revenue ratio to decline over 2026-2028 as revenue rises, but remain high, averaging 27% (‘B’ median: 14%), with the federal government ratio remaining above 50%, constraining fiscal flexibility.
Government debt/GDP is expected to decline and average 32% in 2026-2028 from 40% in 2024, driven by strong nominal GDP growth. Banks’ ample liquidity and strong demand for government securities should support domestic financing capacity.
“We forecast real GDP growth of 4.3% in 2026 (2025: 4%), driven by stronger non-oil activity and continued oil sector growth.
“Persistently high inflation, further pump price increases and heightened security risk could weaken household income and our baseline. We expect growth to remain above 4% in 2027-2028 amid stronger non-oil momentum.
Ratings analysts said almost all banks met the higher paid-in capital requirements introduced at the end of 1Q 2026 by raising fresh core capital. Fitch estimates many banks now have capital adequacy ratios above 20%, supported by recapitalisation and strong profitability.
The global ratings agency said buffers above the 15% minimum for internationally authorised banks and 10% for all other licensed banks provide substantial room for loan and business growth. NESG, FG Call for Actionable Solutions to Translate Economic Reforms into Jobs, Shared Prosperity
