
Hang Seng Index Rises on AI Momentum, US, European Markets Dip
Renewed appetite for technology and AI names is lifting Asian risk sentiment and extending Friday’s US rebound, despite caution ahead of inflation data and major sector earnings, a stockbroking and portfolio management subsidiary of First National Bank (FNB) said in a brief on Monday.
The Hang Seng Index is up 0.20%, supported by technology shares and optimism about China’s AI industry, while the Nikkei 225 has gained 3.15% so far.
Australia’s ASX 200 closed 0.10% higher, with caution around Chinese data and the Reserve Bank of Australia’s inflation warning tempering gains.
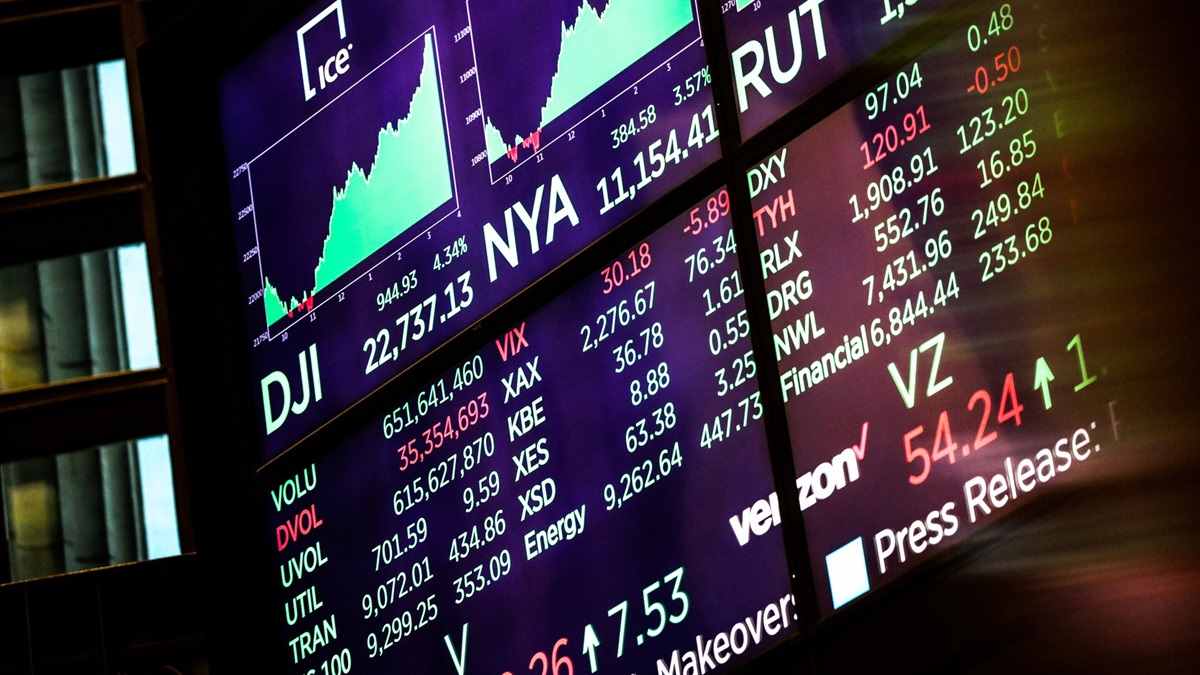
On Wall Street, softer inflation hopes and lower Treasury yields supported Friday’s session, leaving the S&P 500 up 0.31% and the NASDAQ 1.09% higher, although the Dow Jones fell 0.46%.
Attention now turns to Tuesday’s CPI and Friday’s PPI for Federal Reserve policy signals, alongside AI-related earnings and uncertainty around Nvidia (+2.78%).
Europe remained the weak point as deteriorating AI sentiment and falling oil prices pressured heavyweight sectors. The FTSE 100 ended the week down 1.01%, while the Euro Stoxx 50 lost 0.98%.
In South Africa, the Johannesburg Stock Exchange (JSE) is set for a firmer open this morning, recovering from the previous session’s decline as global futures hold a constructive tone and Asian markets are trading higher.
A rebound in Taiwan and gains in Indonesia reinforce the regional advance, although rising Japanese bond yields and a firmer yen, following hawkish Bank of Japan signals, are tempering risk appetite.
Tencent is edging 0.10% higher, offering a modestly positive read through for Naspers and Prosus. On the resources side, the S&P/ASX 300 Metals and Mining Index is up 3.13%, which bodes well for JSE miners, with copper’s rebound on tightening Chinese supply providing an additional tailwind for diversified resource counters.
South African equities closed lower on Friday, with the broader market edging lower as a sharp sell-off in industrials offset strong gains in resources. The All Share Index fell 0.48%, while the Top 40 also came under pressure losing 0.49%.
Resources were the standout performer, rising 1.12%, supported by strength in precious metals (+2%) as gold rebounded following a post-US midterm pullback in the US dollar and Treasury yields, providing a tailwind for rand-hedge miners.
Industrials weighed on the market, declining 1.69%, led by Shoprite (-1.80%) after its first four months’ sales update, and Sappi (-13.66%) which recorded a steep decline after releasing disappointing full-year results and a soft outlook.
Financials were also weaker, down 0.60% as South Africa’s long-dated government bonds sold off. On the political front, municipal election preliminary results added a degree of domestic uncertainty around coalition negotiations across seven of South Africa’s eight largest cities.
