
Nigeria Needs 28% Growth Annually to Hit $1trn Economy – CIoD
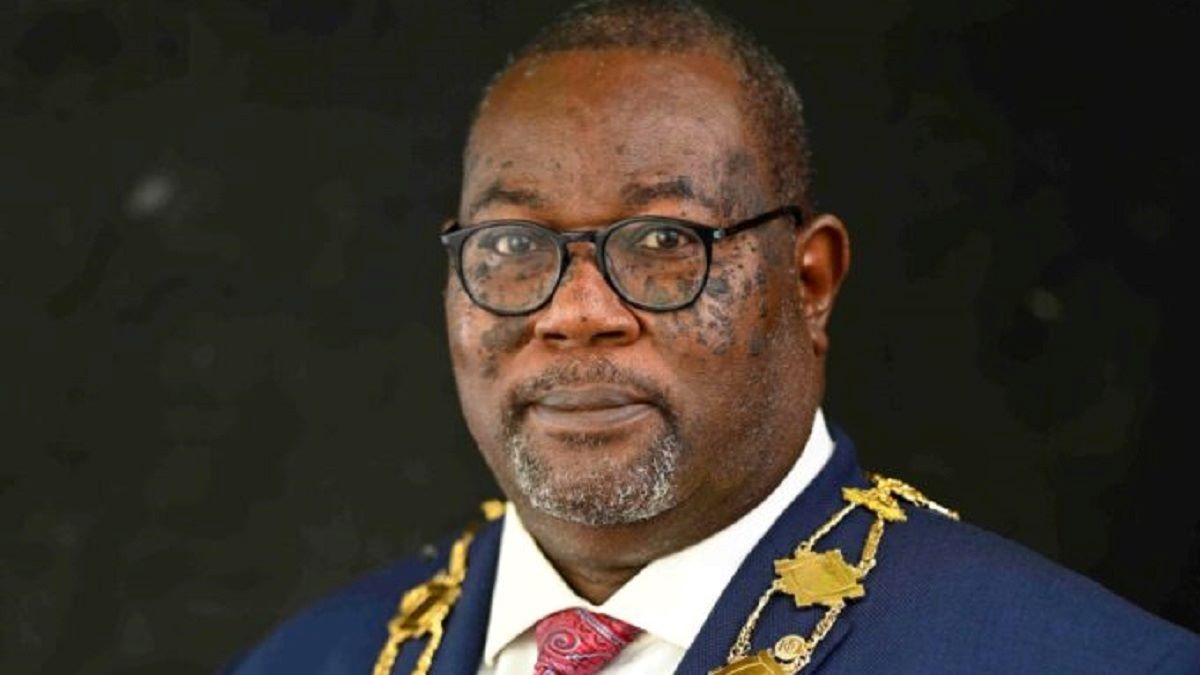
The President, Chartered Institute of Directors Nigeria (CIoD), Mr Adetunji Oyebanji, says Nigeria needs 28.02 per cent annual growth to achieve a $1 trillion economy by 2030.
Oyebanji said this on Thursday in Lagos in his keynote address at the 42nd Omolayole Management Lecture.
He said the 28.02 per cent compound annual growth rate was required to raise Nigeria’s estimated 2025 nominal Gross Domestic Product (GDP) of $290.79 billion to $1 trillion by 2030.
According to him, the required growth rate was aggressive and had no historical precedent for an economy of Nigeria’s current size. “The ambition cannot be achieved through incremental improvement or business-as-usual policies.
“There is a need for sustained acceleration in economic growth, structural transformation and investment,” he said. Oyebanji identified power deficits, infrastructure gaps, oil sector inefficiencies, and foreign exchange volatility as structural constraints limiting Nigeria’s economic expansion.
He also listed low tax-to-GDP ratio, insecurity, policy inconsistency and human capital deficits among the factors constraining economic growth.
He said Nigeria needed to move beyond reliance on its economic resources and focus on building effective institutions and ensuring policy consistency.
He added that the country must create an environment conducive to private-sector investment and industrial expansion.
“Economic potential alone does not guarantee economic size.
“It will be achieved through disciplined governance, effective institutions, consistent policies, and a shared commitment to national development,” he said.
Oyebanji noted that recent reforms in monetary policy, tax administration and the petroleum sector were contributing to improved economic conditions, investment certainty and fiscal sustainability.
He said the Central Bank of Nigeria’s reforms had contributed to moderation in inflation, improved foreign exchange market stability and stronger investor confidence.
He added that tax administration reforms could improve domestic revenue mobilisation and reduce dependence on oil revenue.
According to him, petroleum sector reforms could enhance transparency, investment certainty and production potential.
“Sectors such as oil and gas, agriculture and agro-processing, manufacturing, technology and the digital economy will be critical to expanding the economy,” he said.
He also identified infrastructure, solid minerals, services and the creative industry as critical sectors for economic expansion.
The CIoD president identified 10 strategic pillars required to drive the transformation, including macroeconomic stability, institutional strengthening and policy consistency.
Others, he said, were regulatory certainty, infrastructure development, domestic revenue mobilisation, private-sector and investment promotion, industrialisation and diversification.
He also listed human capital development, technology and digital transformation, governance, transparency and the rule of law.
Oyebanji added that Nigeria must accelerate investment across productive sectors, strengthen infrastructure, maintain fiscal and monetary discipline and expand exports.
He also called for improved industrial competitiveness, deeper development of the digital economy and stronger domestic revenue mobilisation.
He urged the government to maintain policy consistency to restore and sustain investor confidence.
The CIoD president said achieving the target should ultimately be measured not only by GDP size but also by improvements in Nigerians’ quality of life.
He urged the government to pursue reforms that strengthen institutions and productivity, while placing long-term national development above short-term considerations.
Oyebanji also called on the private sector to invest with confidence and patience and build globally competitive and productive businesses.
He urged Nigerians to embrace innovation, entrepreneurship, productivity and excellence, saying shared prosperity was a collective responsibility. Tinubu Pledges Policy Stability as Ogun Attracts $7bn Investment
