
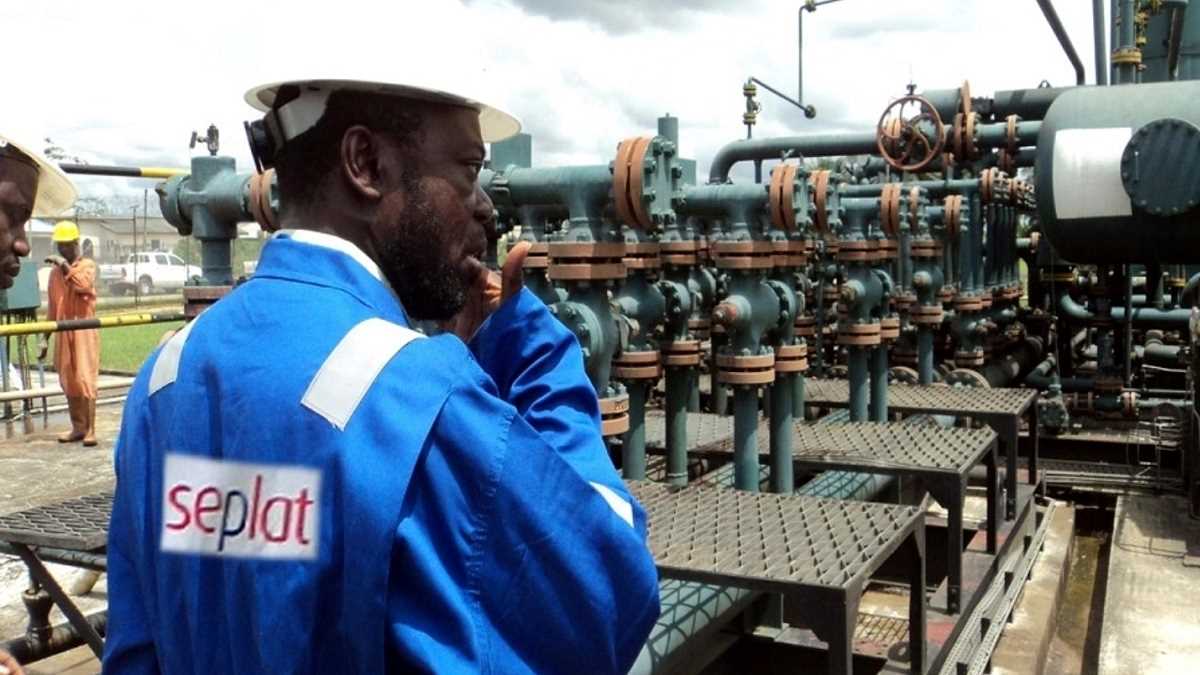
Seplat Energy Target Price Hikes to N17,588 at CardinalStone
Seplat Energy Plc 12 months target price has been adjusted upward to N17.588.87 at CardinalStone Securities Limited from N16.454.41, with hold recommendation.
Equity analysts estimated 8.3% upside potential for the energy company, which closed at N16.241.90 on the Nigerian Exchange (NGX) on Friday, with market capitalisation at N9.744 trillion.
In its equity report, CardinalStone Securities Limited said Seplat Energy Plc continues to show upward earnings momentum, with Profit After Tax (PAT) surging 2.7x to $260.2 million in 9M 2026.
The investment firm said this performance reflects improved operational efficiency, supported by higher realised prices, noting that the benchmark Brent crude price averaged $88.22 per barrel, up from $69.94 in the equivalent period in 2025.
SEPLAT reported an average realised price of $96.19 per barrel during the review period, versus CardinalStone’s previous estimate of $85.00 per barrel for 2026, about a 9.0% premium to Brent.
Analysts said the successful integration of wells from the completed 2025 drilling plan and the 2026 idle well restoration programme continues to support overall working interest production volumes.
“The well restoration programme has added over 64.0 kboepd year-to-date in gross production capacity, with 41 of 50 wells planned for 2026 already restored.
“However, following the planned sell-down of 10.0% interest in the NNPCL – SEPNU joint venture (NNPCL – SEPNU JV), we stepped down production volume assumptions over our forecast period (2027 – 2031), translating to revenue of $3.6 billion by 2030 (vs $4.3 billion in previous forecast)”.
Elsewhere, CardinalStone Securities Limited highlighted the delay in converting SEPLAT’s offshore assets to the Petroleum Industry Act (PIA) framework.
Analysts explained that the company recently disclosed that, following further regulatory engagement, the Nigerian Upstream Petroleum Regulatory Commission (NUPRC) indicated that the original conversion window had elapsed.
“Although the Group continues to engage with the regulator and other relevant stakeholders to assess available options for the offshore assets, we have conservatively increased our forecast effective tax rate to a mean of about 64.0% for the next half-decade from 54.0% previously, maintaining the current fiscal structure of the business”.
The investment firm said it also noted that OMLs 67, 68 & 70 (offshore assets) are due for renewal by FY’31, after which they automatically convert to the PIA regime if the conversion has not already occurred.
Between 2026 and 2031, CardinalStone expects Seplat revenue to decline at a modest cumulative average growth rate (CAGR) of 1.7%, reflecting the normalisation of oil prices over the forecast period, the impact of the 10.0% working interest divestment at the NNPCL–SEPNU JV, and the current fiscal framework.
Nonetheless, the investment firm said it still expects better realised oil prices than previous forecasts, improved hydrocarbon monetisation, cost optimisation, and resilient free cash flows, translating to a net income CAGR of 4.9% over the same period.
Consequently, analysts at CardinalStone Securities Limited updated the 12-month target price of Seplat to N17,588.87/share from N16,454.41/share, implying an 8.3% upside and a Hold recommendation
“We now expect 2026 Group production to settle at 147.0 kboepd, from 145.0 kboepd as at 9M’2026 and 139.5 kboepd in H1’26.
“This projection aligns with SEPLAT’s updated production guidance of 145.0–155.0 kboepd, reflecting the company’s improved year-to-date performance.
“Our forecast implies an 11.8% year-on-year growth in working interest production volumes. We raise our onshore volume expectations to 68.1 kboepd (vs 62.6 kboepd previously), driven by higher gas production as ANOH increased its contribution, as SEPLAT reported the first commercial gas sold via the OB3 pipeline.
“As a result, we forecast onshore gas volumes at 168.0 MMscfd for 2026, before averaging 222.7 MMscfd over our forecast horizon, as ANOH contributions strengthen”, CardinalStone said in the review.
The firm explained that contributions from new wells brought online through the 2025 drilling programme, 8 new wells delivered in 9M’26, and other scheduled well deliveries in Q4’26 should also support onshore production growth via liquids.
“We also view the improvement in onshore deferments as a positive catalyst for output, following the resumption of activities in the Trans Forcados Pipeline (TFP) after its Q1’26 outage. CardinalStone Securities Limited forecasts average daily liquids production of 39.2 kbopd for the financial year 2026. Oil Prices Surge as US Strikes Iran’s Island, Brent Tops $106
