
Custodian Investment at N63: Is a N100 Target Within Reach?
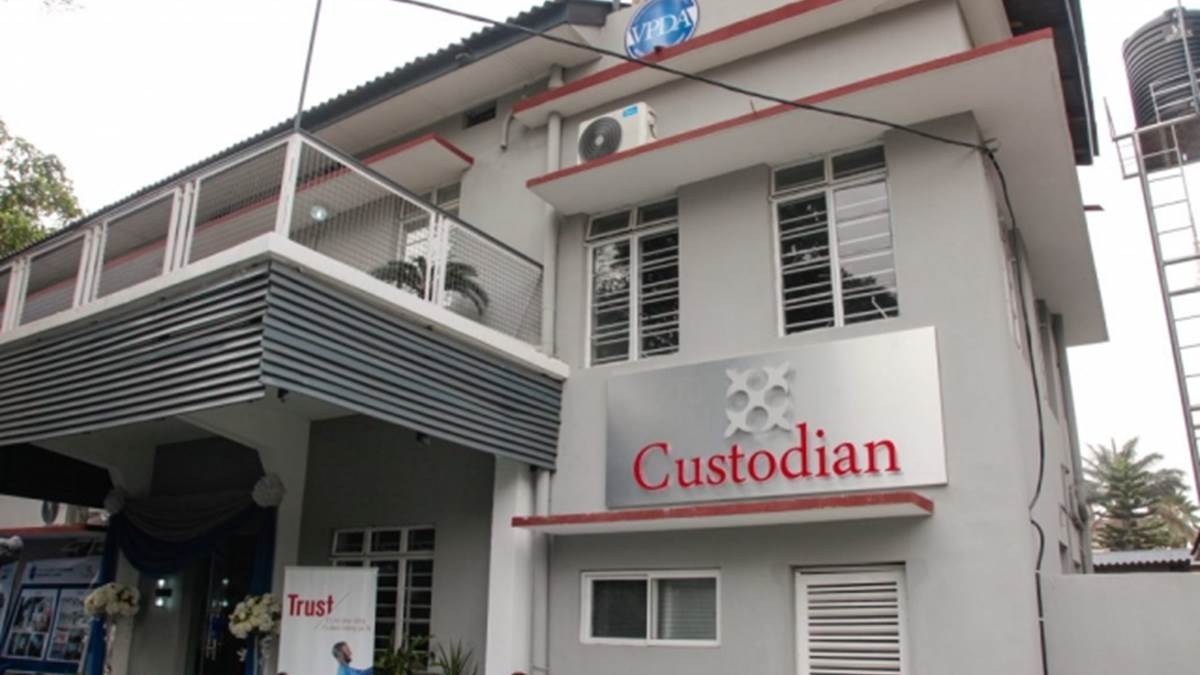
Custodian Investment Plc is increasingly presenting an interesting valuation proposition on the Nigerian Exchange (NGX), with its latest nine-month financial performance reinforcing the investment case for shareholders willing to look beyond near-term market volatility.
The company’s financial results for the period ended September 30, 2026, demonstrate meaningful growth in revenue, profitability and balance-sheet capacity. Yet its share price has slowed, closing at N63.00, below its 50-day moving average of N69.14 and its 52-week high of N89.95.
For fundamental investors, the divergence between improving corporate earnings and weakening share-price momentum demands attention.
Custodian Investment delivered gross revenue of N255.41 billion for the nine months ended September 2026, up 46.92% from N173.85 billion in the corresponding period of 2025.
Profit before tax rose 25.52% to N66.20 billion from N52.74 billion, while profit after tax rose 26.17% to N57.59 billion from N45.65 billion.
These numbers reflect an expanding earnings base, supported by stronger investment income, improved insurance service profitability and higher interest earnings.
Notably, interest income surged 232.01% to N110.14 billion from N33.17 billion, while the group’s investment result climbed to N123.45 billion from N82.39 billion.
The insurance business also demonstrated improved underlying profitability. Insurance service results increased 43.87% to N17.65 billion, despite a 4.81% contraction in insurance service revenue.
However, the earnings narrative comes with caveats. Management expenses more than doubled to N29.95 billion, while net insurance finance expenses increased to N39.39 billion.
These cost pressures warrant close monitoring because sustained revenue growth must ultimately translate into stronger earnings per share.
At N63.00 per share, Custodian Investment trades at about 1.57 times book value, based on valuation metrics. Its reported return on assets of 4.12% and return on equity of 20.69% further suggest an attractive capacity to generate returns from its asset and equity base.
Reported nine-month earnings per share stand at N8.27, up from N7.59 in the corresponding period of 2025, representing growth of approximately 8.96%.
Annualising the nine-month EPS produces an indicative earnings run rate of approximately N11.03 per share. At the current N63.00 market price, this translates into a forward-looking earnings multiple of approximately 5.7 times.
This valuation may be attractive for a diversified financial services group showing double-digit profitability growth. Importantly, the N11 earnings figure should be understood as an annualised earnings estimate rather than reported nine-month EPS. The actual nine-month result is N8.27.
The distinction matters because investors should assess whether fourth-quarter earnings can sustain the trajectory needed to deliver about N11 in full-year EPS.
From a technical perspective, the stock’s recent price correction presents a more cautious picture. At N63.00, the share price trades approximately 8.9% below its 50-day moving average of N69.14 and nearly 30% below its 52-week high of N89.95.
This suggests near-term buying momentum has weakened, potentially reflecting profit-taking and market rotation aligned with a broader reassessment of valuation after the previous price appreciation.
Nevertheless, a declining share price does not automatically invalidate an improving earnings outlook. For investors with a longer investment horizon, the current weakness could offer an opportunity to gradually accumulate exposure, provided the company’s underlying financial performance remains intact.
A sustained recovery above the N69.14 moving average would offer a more convincing technical signal that bullish momentum is returning. The long-term investment proposition becomes particularly interesting when earnings growth is considered alongside valuation.
Sustained annual EPS of approximately N11 would put the stock at roughly 5.7 times earnings at N63.00. At N100.00, the same earnings base would imply a valuation of approximately 9.1 times earnings.
This framework helps explain the potential upside: earnings expansion and a valuation re-rating could drive meaningful share price appreciation. Moving from N63.00 to N100.00 represents approximately 58.7% capital appreciation.
While N100.00 is an ambitious long-term valuation proposition rather than an immediate price target, it is not unreasonable if earnings growth, capital efficiency, investment returns, and market confidence remain supportive over the coming years.
The key catalyst will be the company’s ability to translate its expanding asset base into sustainable shareholder earnings.
Investor’s recommendation: Accumulate on weakness, but remain earnings-focused
Custodian Investment’s nine-month financial performance reinforces its position as an interesting fundamental investment proposition within Nigeria’s diversified financial services space.
The combination of 46.92% revenue growth, 25.52% pre-tax profit expansion, 20.69% reported ROE and an indicative annualised EPS above N11 presents a compelling starting point for valuation analysis.
Nevertheless, investors should not overlook slower EPS growth relative to profit after tax, elevated management expenses, rising insurance financing costs, and weaker operating cash flow.
These are important considerations when evaluating the sustainability of earnings growth. The investment stance is ACCUMULATE, with a medium-to-long-term horizon.
Investors already holding the stock may consider maintaining their positions while monitoring earnings quality and price recovery. Prospective investors could consider accumulating in stages rather than committing their entire investment at once.
The N100.00 price region represents a potential longer-term valuation destination, conditional on sustained earnings expansion and a favourable market re-rating. It should not be interpreted as a guaranteed outcome.
Ultimately, Custodian Investment’s investment appeal rests on a straightforward proposition: if the fundamentals continue to strengthen while the market valuation remains relatively restrained, the current price weakness could prove to be an opportunity rather than a deterioration in the underlying investment story.
The market may be pricing the recent slowdown. Fundamental investors, however, should be watching the earnings trajectory.
Oil Prices Surge as US Strikes Iran’s Island, Brent Tops $106
